.png) 7 hours ago
3
Upgrade to High-Speed Internet for only ₱1499/month!
Enjoy up to 100 Mbps fiber broadband, perfect for browsing, streaming, and gaming.
Visit Suniway.ph to learn
Keisha Ta-Asan - The Philippine Star
November 5, 2026 | 12:00am
In a note, GlobalSource Partners economist Diwa Guinigundo said the central bank’s recent 50-basis-point increase was aimed at addressing mounting price pressures and preventing inflation expectations from becoming entrenched.
Businessworld / File
MANILA, Philippines —The Bangko Sentral ng Pilipinas (BSP) should not be judged by the peso’s immediate reaction to its latest interest rate hike, as monetary tightening is primarily intended to contain inflation rather than defend a particular exchange rate, according to GlobalSource Partners.
In a note, GlobalSource Partners economist Diwa Guinigundo said the central bank’s recent 50-basis-point increase was aimed at addressing mounting price pressures and preventing inflation expectations from becoming entrenched.
“The BSP did not raise interest rates primarily to defend the peso. It did so to address mounting inflationary pressures and prevent inflation expectations from becoming unanchored,” Guinigundo said.
The BSP raised its benchmark policy rate to 5.50 percent last month as inflation accelerated to 7.2 percent in September, well above the government’s two to four percent target.
Guinigundo said the continued weakening of the peso following the BSP’s rate increase had raised questions about the effectiveness of monetary policy, with some observers describing the move as futile.
The local currency weakened to a record low of 64.17 against the dollar on Oct. 27 before recovering to the 63-per-dollar level recently.
The former BSP official stressed that not every episode of peso depreciation warrants an interest rate increase, nor should every rate hike be expected to produce an immediate appreciation of the currency.
He said the BSP’s monetary policy decisions should instead be assessed based on their ability to contain inflation and stabilize expectations over time.
Beyond monetary policy, Guinigundo warned that structural weaknesses continue to expose the Philippine economy to currency volatility.
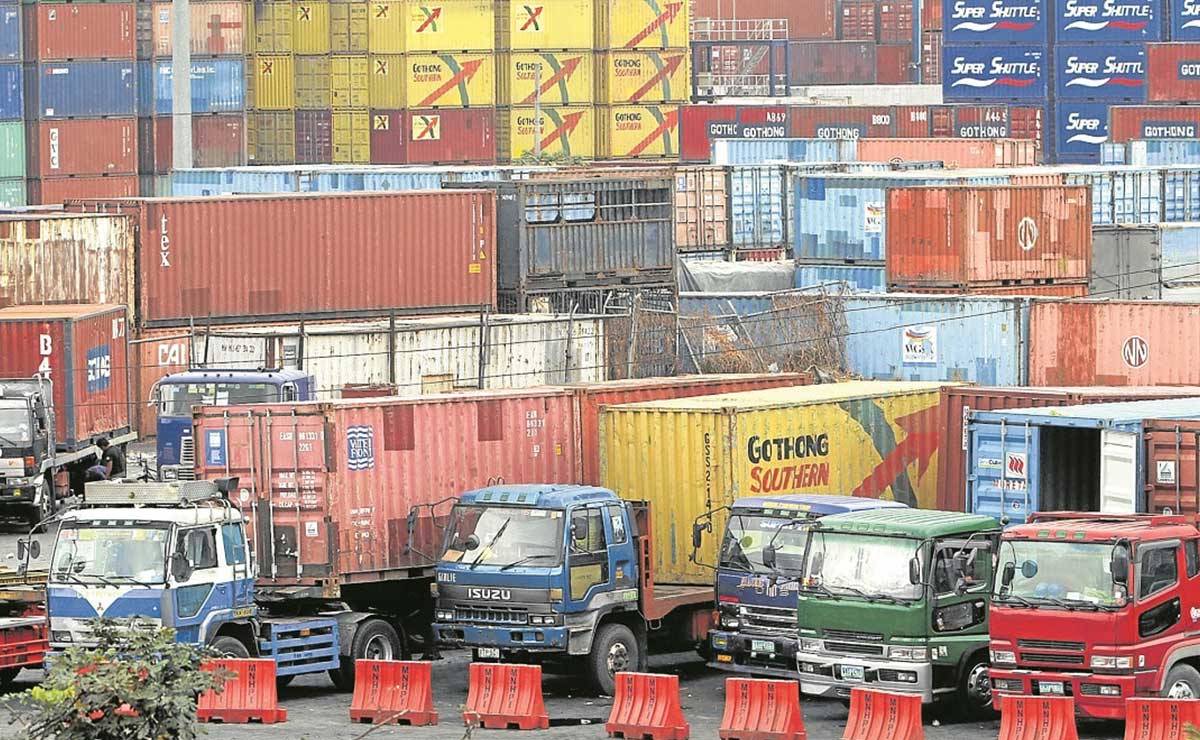
These include persistent trade deficits, heavy dependence on imported energy and production inputs, limited export diversification and recurring foreign financing requirements.
Such vulnerabilities could not be resolved through higher interest rates or repeated intervention in the foreign exchange market alone, he said.
“The objective must be to increase the country’s capacity to earn foreign exchange, not merely manage its demand for dollars,” Guinigundo said.
He called for improvements in agricultural and manufacturing productivity, lower energy and logistics costs, more competitive exports and greater efficiency in public investments.
Guinigundo also suggested exploring incentives that would encourage overseas Filipino workers and business process outsourcing firms to retain and invest more of their foreign currency earnings domestically, provided these offer attractive returns and adequate safeguards.
He said that government efforts to strengthen confidence should complement monetary policy without undermining the central bank’s operational independence.
He also said that sustainable currency stability would ultimately require stronger exports, productive investments, sound fiscal management and credible institutions rather than relying solely on monetary tightening.
“A rate hike is not a peso defense strategy. It is an instrument for protecting purchasing power and containing inflation. Its effectiveness must be assessed on that basis,” he added.